Target renewal timing and a specific coverage gap
Commercial insurance outreach works best when it is tied to two things: a renewal window and a plausible coverage gap for that business type. A general contractor, a healthcare practice, and a logistics company each carry different exposure, and a message built around 'save on premiums' ignores that entirely. Before building your list, pick one or two industries you understand well enough to name a real gap, undervalued equipment, outdated liability limits, cyber exposure that has grown faster than the policy, and build your ICP around companies in that industry and size range.
Write out the gap in one plain sentence before you touch FirstSales: what changed about this kind of business over the last two or three years that most existing policies have not caught up with. That sentence becomes the spine of every email you send in the campaign.
Different business sizes carry the same gap differently. A ten-person contractor and a two-hundred-person contractor both face equipment-valuation gaps, but the conversation with each looks different, one owner handles this personally, the other routes it through an operations lead. Decide which size band this campaign targets before you write the offer description.
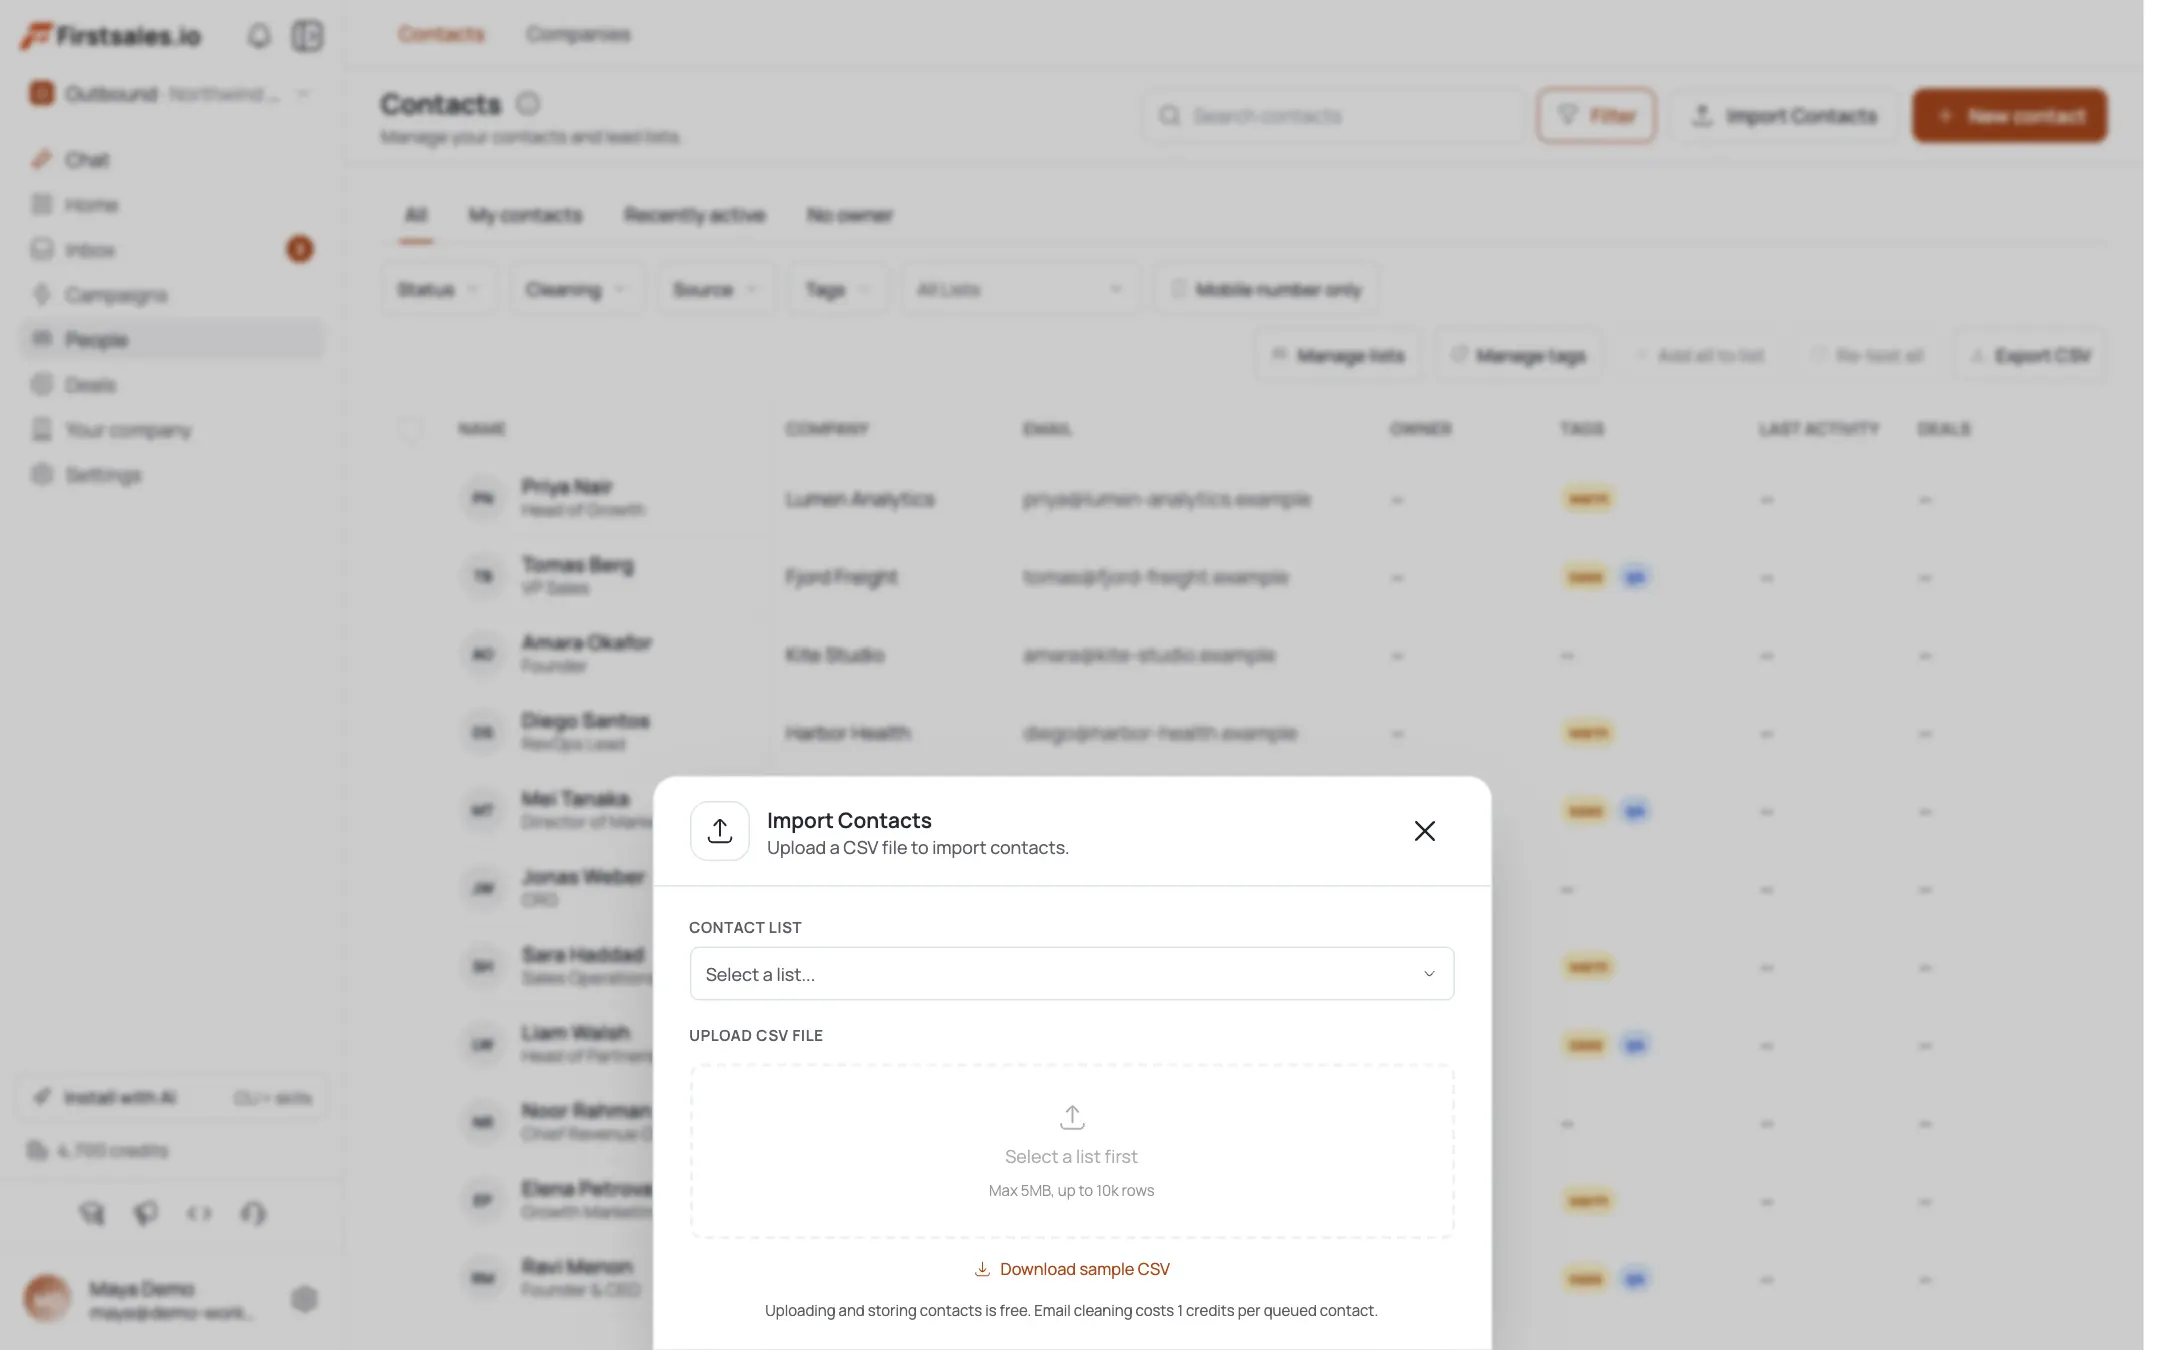
Build your list with AI Leads around industry and company size
Describe your target in AI Leads: industry, headcount or revenue range, and the titles who handle insurance decisions (owner, CFO, VP of Operations, sometimes a dedicated risk manager at larger companies). The quality funnel filters weak matches before they cost credits. If you already track renewal dates through your agency's own system, import that list as a CSV so FirstSales can focus on research and drafting.
Keep the industry narrow enough that the gap you identified actually applies to every company on the list. A list that mixes adjacent industries forces you back toward generic language in the next step, which undoes the specificity that makes this approach work.
Use contact research to find the coverage-relevant detail
Contact research runs automatically before drafting, and the transparency view shows what it found and what made it into the email, company facts, role, and public signals. For this audience, look for details that hint at exposure: new equipment purchases, a new location, headcount growth, or a shift in what the business does. A specific operational detail, not a generic 'protect your business' line, is what gets a risk-aware buyer to read past the first sentence.
When the research view turns up nothing specific for a contact, fall back to the industry-level gap you defined in step one rather than forcing a detail that is not really there. A general but accurate observation beats a specific but shaky one.
Set up the campaign around a specific gap, not a general pitch
Campaign guidance walks you through Describe, Teach, and Practice. Describe the actual coverage gap you are addressing for this industry, not your agency in general. Teach the AI your positioning around that specific risk. Practice on real drafts and check each one for the same thing an underwriter would check: does this describe an actual exposure, or does it just say 'insurance' in different words?
Set your campaign goal to a coverage review call, not a quote request in the first email.
If your agency covers several risk categories for this industry, pick the one gap you have the clearest evidence for and lead with that. A campaign trying to cover every possible exposure in one email loses the specificity that makes the approach work in the first place.
Read each practice draft as if you were the risk manager receiving it. If the email could apply to almost any industry with a word swapped, it needs another pass before it goes live.
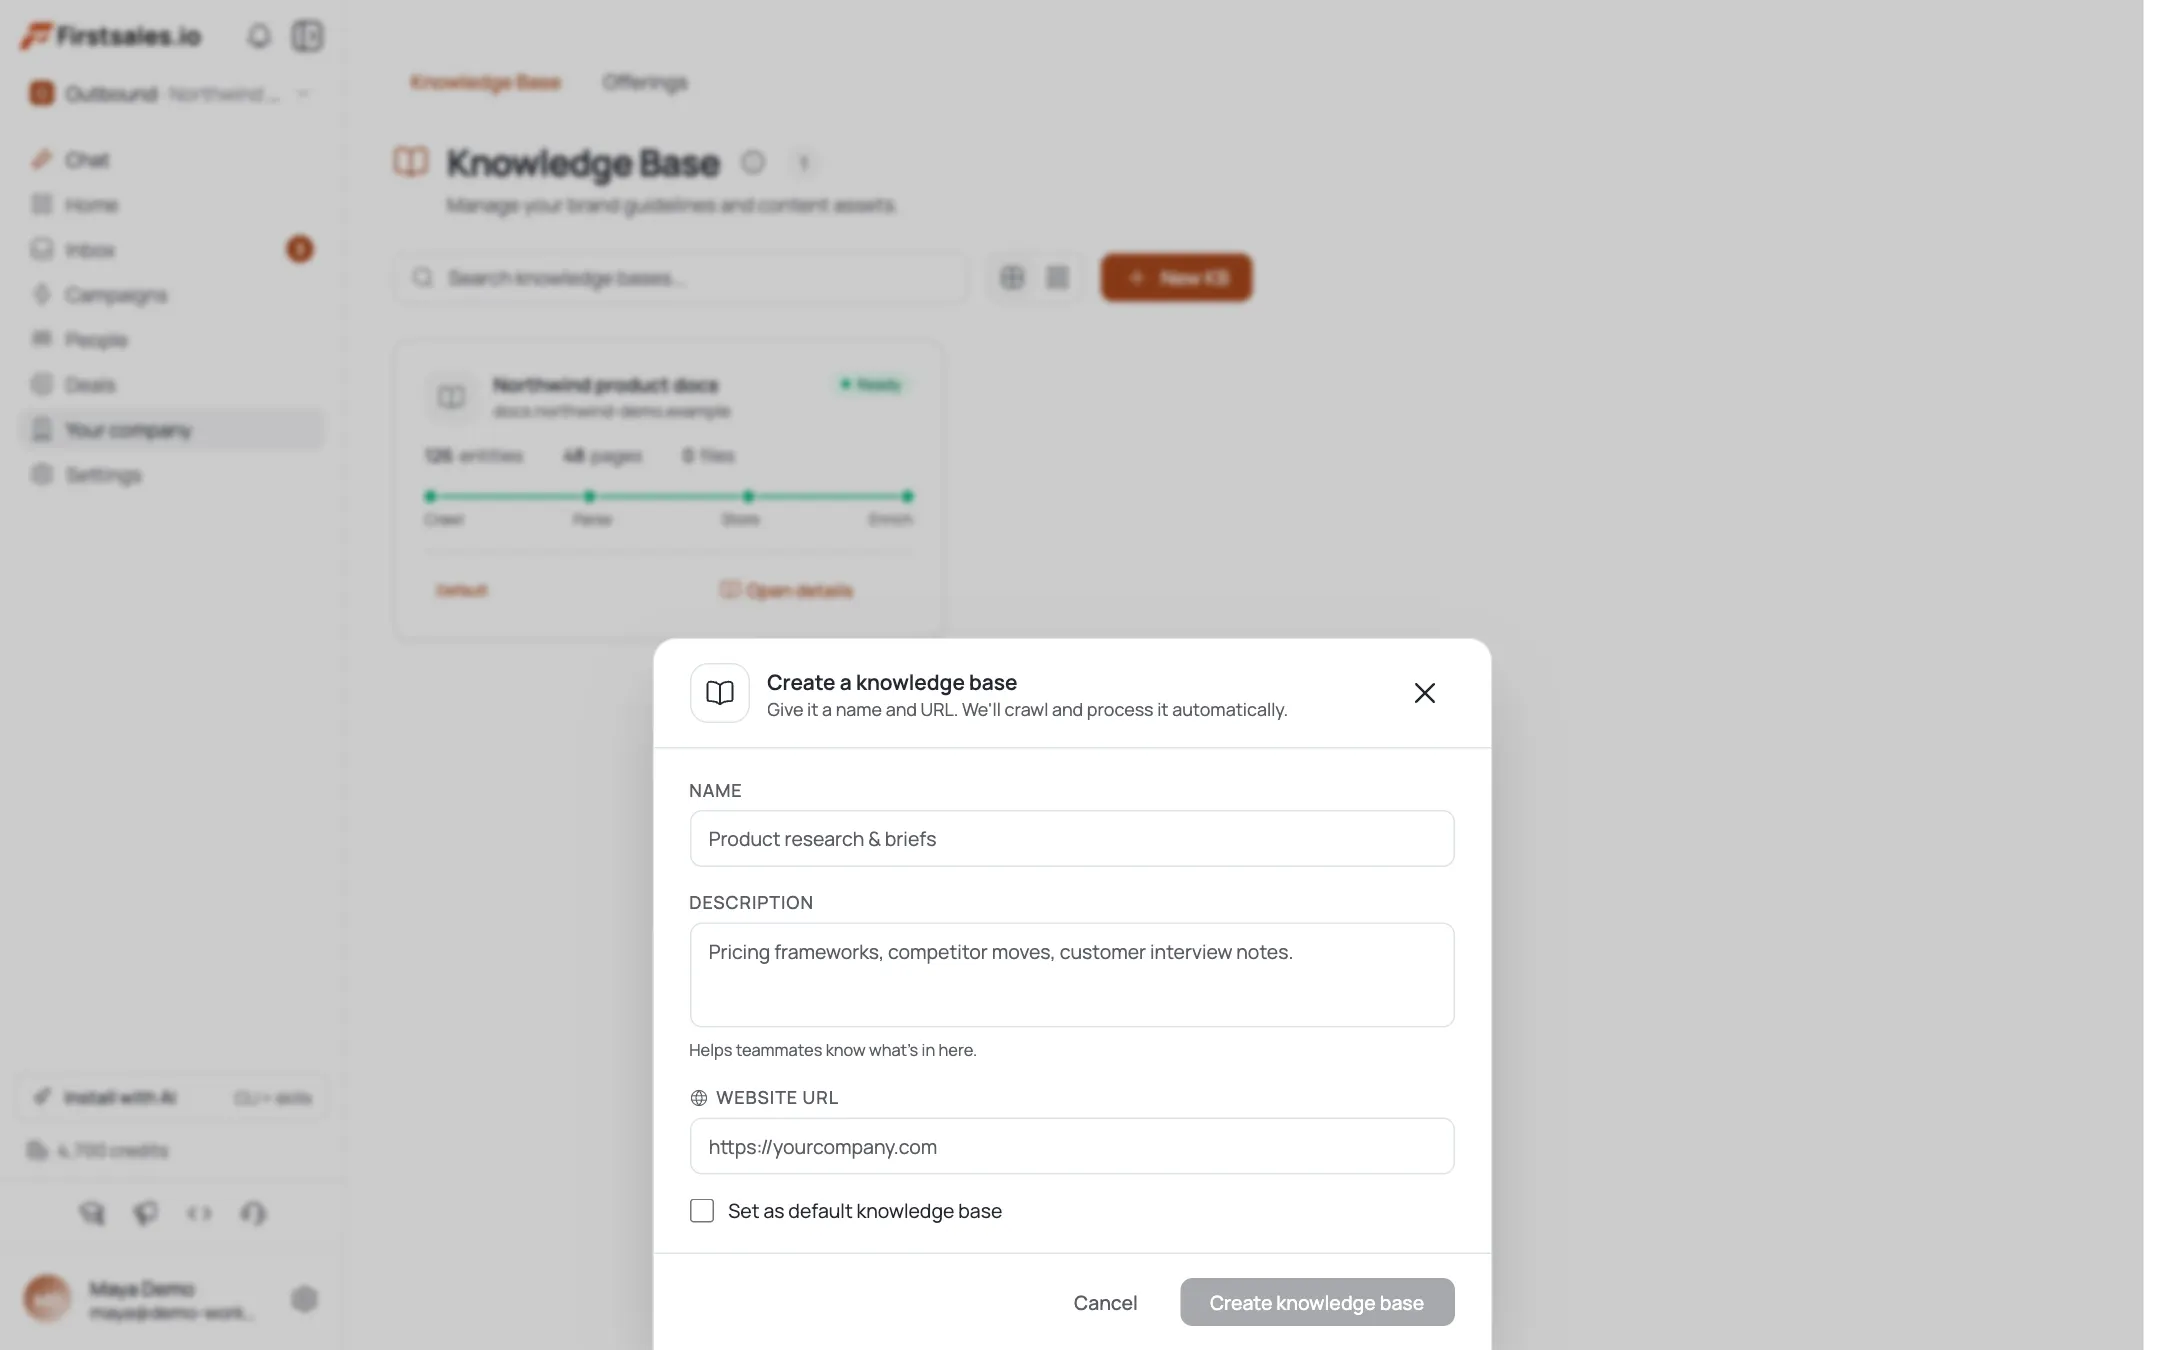
Teach a consultative, specific tone
Paste past emails that earned replies, or write two or three samples in the tone you want. The tone that works here sounds like a risk conversation, not a rate quote. Name the exposure plainly, explain in one sentence why it matters for this kind of business, and ask a direct question about whether their current policy addresses it. Avoid price-first framing, 'save 20% on your premium' reads as a commodity pitch and this audience wants a specialist.
If you have reviewed similar policies before and found the same gap repeatedly, a plain, factual mention of that pattern (without naming other clients) helps the reader see this as a known issue in their industry rather than a sales angle invented for the email.
Keep sentences short here too. A risk manager or owner reading a cold email about coverage wants the point made in the first two sentences, with the reasoning behind it in the third.
Time your sequence to the renewal calendar
Design your sequence to start sixty to ninety days ahead of a typical renewal window for the industry you are targeting, with three to four steps spaced a week or two apart. Steps stop automatically on reply. Renewal timing is one of the few triggers in commercial insurance you can predict with reasonable confidence, industry-typical renewal cycles are public knowledge, so build your calendar around that instead of guessing at individual policy dates.
If you serve multiple industries with different renewal seasons, run separate campaigns timed to each one rather than one continuous campaign. That keeps your compliance review, your messaging, and your calendar all aligned to the same window.
Handle replies with the specific gap top of mind
Replies land in a unified inbox, and AI reply handling can manage scheduling and simple questions. Bounce handling auto-suppresses bad addresses so your list stays clean. When a reply asks for a quote, resist quoting blind. Move to a short call first, a coverage review conversation surfaces the actual exposure and usually leads to a better quote than one built off a cold email alone.
If a reply says the business already reviewed this exact gap recently, take that as useful information rather than a rejection. Ask what they found, it often opens a conversation about a different, related exposure you can speak to.
Track results by industry angle, and keep compliance in view
Standard B2B outbound in this space typically lands in the 2 to 5 percent reply range, and reply quality varies a lot by how specific your coverage-gap angle is; a vague premium pitch usually underperforms a specific exposure pitch by a wide margin. If your agency or carrier partner operates under FINRA Rule 2210 or a similar communications standard, route sequence copy through that review before launch. Avoid promising savings amounts or coverage outcomes in writing, keep every claim about gaps and exposure factual and let the review call do the persuading.
Review your results after each renewal season and note which coverage-gap angle produced the most calls that actually converted into a review, not just the most replies. A narrower angle that consistently leads to real conversations is worth more than a broader one that generates interest without follow-through.
Subject: a gap we see a lot in [industry]
Hi [First name],
Noticed [Company name] has added [equipment/location/headcount] recently. That kind of growth is exactly where we usually find policies that haven't kept pace, coverage sized for the business two years ago, not the one running today.
Worth a short call to walk through where your current policy might have a gap? No obligation, just a second look.
[Name]
Dicas de especialista
Name the coverage gap up front
Name the gap in the subject line or first sentence. 'A gap we see a lot in [industry]' earns more opens than any subject mentioning your agency's name.
Rotate gaps by industry and research
Build a short list of the three most common gaps for each industry you target, and rotate which one leads the email based on what contact research actually surfaces for that company.
Give a range, not a refusal
When a reply asks for a number before a call, give a realistic range and explain why a proper quote needs the coverage review first. A flat refusal to discuss numbers loses the reply.